24*7 access anytime anywhere


In the same week, two neighboring homes in the same apartment block decide to purchase life insurance in Nepal.
Both wish for a guaranteed amount of Rs. 10,00,000. One walks out paying a premium that feels manageable.
The other one is almost double the quoted price for the same coverage. Nothing about the numbers looks unfair once you understand how insurers actually price a policy, and that is exactly what this guide breaks down.
Key Takeaways
Life insurance premiums in Nepal are built around age, sum assured, policy term, plan type, and payment frequency, not a single flat rate.
Health status, occupation, and optional riders such as critical illness cover can raise or lower the final premium.
Term plans cost far less than endowment or money back plans for the same coverage, because the two products are built for different purposes.
Purchasing early, selecting a realistic term, and making annual rather than monthly payments are practical strategies to maintain premium efficiency without reducing coverage.
In this guide, you will learn how each of these factors can be used to calculate a premium, determine what you can and can't control, and what you can do right now to secure the best rate.
A premium is the amount of money that you pay, typically yearly, for the insurer to cover a sum assured to your family in the event of your death, or to you at maturity for savings-related plans.
It is not an arbitrary number set by an agent.
It is a consensually determined assessment of risk, the expenses incurred in handling the risk, and, for participating plans, a portion of the bonus that the insurance company anticipates earning over the policy term.
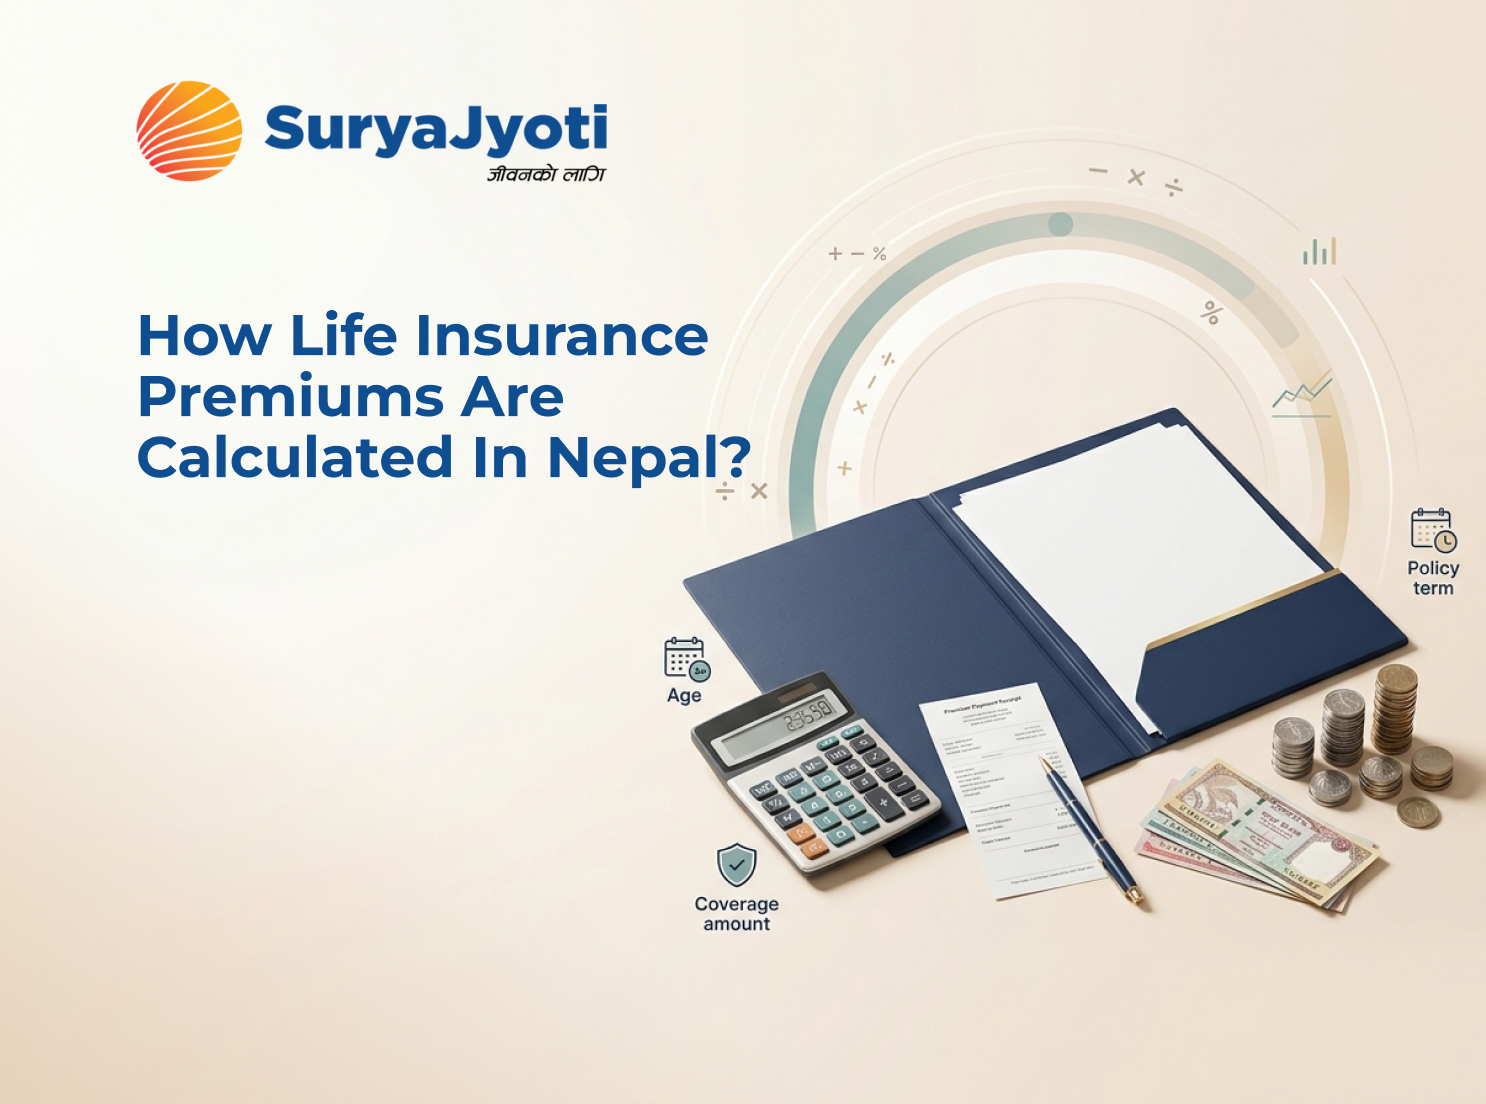
As confirmed on SuryaJyoti's own product pages, premium is determined mainly by the age of the insured, the policy term chosen, and the requested coverage amount.
Everything else layered on top, health, occupation, gender, and add on riders, adjusts that base calculation up or down.
The older you are, the higher the risk of death in the near future, which directly impacts the premium.
The 25-year-old will pay much less for the same policy than the 45-year-old.
This is the most crucial element in calculating the premium for any life insurance policy in Nepal, and it also has an immediate impact on when to buy life insurance.
A 25-year-old applying for a 20-year endowment plan with a Rs. 10 lakh sum assured will pay a meaningfully lower annual premium than a 40-year-old applying for the exact same plan.
And once the policy is issued, that rate is locked in for the entire term. It does not increase as you age.
This is why starting life insurance early in Nepal is consistently the most financially sound advice an insurance professional can give.
Every year you delay is a year at a higher age entry point, permanently increasing the premium for the same coverage.
The amount your family will receive upon your demise is called the sum assured, or the amount you receive at maturity.
The higher the sum assured, the higher the premium, proportionally, since the insurer's mortality exposure and the savings corpus both scale with the coverage amount.
Choosing the right sum assured requires honest calculation: outstanding loans, years of income the family would need to replace, and children's education costs.
The guide on how much insurance coverage Nepalis actually need walks through this calculation in practical terms.
Longer terms will result in a lower annual premium when the same amount of insurance is purchased, because the premium is spread over a longer period.
However, the total premium paid over a longer term is typically higher than over a shorter one.
This relationship between term and premium is different with each plan type, and the SuryaJyoti Premium Calculator allows you to compare the costs of different terms for the same coverage in minutes.
This is where the savings component comes in. To grasp the life insurance premium calculation in Nepal, it's essential to understand what your premiums represent, depending on the type of life insurance plan.
A term plan, such as SuryaJyoti Surakchya Kawach Myadi Jeevan Beema, has the lowest premium for the sum assured compared to other plan types and does not offer savings or maturity benefits.
An endowment plan like the Sawadhik Jeevan Beema carries a higher premium because it simultaneously builds a savings corpus that matures with the sum assured and bonus at the end of the term.
A money back plan like the Three 20 Dhan Bahar Jeevan Beema is priced to fund both the periodic payouts and the continued life cover throughout.
None of these is more expensive in a wasteful sense, each premium is funding a different set of benefits.
The detailed comparison of term life insurance versus endowment plans helps make this distinction concrete.
How life insurance premiums are computed in Nepal is directly influenced by your health at the time of applying for insurance.
Most policies above a certain sum assured require a medical examination.
If the examinations reveal risk factors, such as high blood pressure, high blood sugar, or a history of serious illness, the insurance company may add a loading to the standard rate or, in a few instances, refuse to cover certain conditions.
This is known as a substandard risk loading and signifies the actuarial fact that an individual at higher health risk is more likely to make a claim.
One practical way to keep your premium as low as possible is to maintain your good health before you apply.
Worldwide, women's mortality rates and the mortality charges are lower on average than those of males, and in most insurance markets, this results in slightly lower mortality charges for women.
There is evidence that gender-specific risk profiles are being recognized in Nepal's market, and premium structures vary by insurer.
The premium paid by women who take the same plan with the same sum assured as a man of the same age is normally less.
Each policy rider provides additional coverage beyond the basic policy, with an additional premium. The cost is typically expressed as a rate per thousand rupees of sum assured.
The Critical Illness Rider available through SuryaJyoti, which provides coverage for up to 35 critical conditions with a maximum payout of Rs. 50,00,000, carries its own actuarially calculated rate on top of the base premium.
The Accidental Death Benefit (ADB) rider on most SuryaJyoti plans is priced at Rs. 1 per thousand of sum assured, one of the most affordable rider rates in Nepal's market.
The Total Permanent Disability rider with premium waiver benefit is priced at Rs. 2.5 per thousand on plans where it is available.
Riders are worth adding if your risk profile warrants them.
Details about each rider and how their costs are calculated are available on the Critical Illness FAQs page.
The number of payments impacts the annual expense. Annual premium payments are the most cost-effective.
Paying quarterly or monthly involves a small loading because the insurer absorbs additional administrative costs and slightly more financial risk per period.
The difference is small, but for someone who wants to be assured of paying the lowest total over the life of the policy, annual payment may be preferable.
Consider two hypothetical applicants, both wanting Rs. 10,00,000 in coverage over a 20-year term.
A 25-year-old applying for a term plan would typically see one of the lowest premiums available on the market, since age and plan type are both working in their favor.
A 45-year-old requesting the same coverage under an endowment plan would see a considerably higher premium, since both a higher entry age and a savings linked structure push the cost upward.
The above numbers are for illustrative purposes only and not intended to reflect the actual SuryaJyoti premiums.
The exact premium for each applicant will depend on their age, health disclosure, and chosen plan, so you can't be sure what it'll be unless you calculate it yourself.
You cannot control:
- The age at which you make your purchase
- Your current health problems on the date of application
- The mortality tables the insurer uses, which are actuarially standardised and NIA-approved
You can control:
- When you apply, earlier always means lower
- Your health before applying: a medical check-up in advance helps identify and address flaggable conditions
- The sum assured you choose, sized correctly, not over-insured or under-insured
- The plan type, matched to your financial goal rather than chosen arbitrarily
The riders you add, added when genuinely needed, not reflexively
The payment frequency, annual to minimize loading
The combination of these controllable factors can meaningfully change the premium calculation, and therefore the total cost of being insured over a lifetime.
Whatever premium you end up paying, it is worth remembering that life insurance premiums in Nepal qualify for a yearly deduction from taxable income, up to Rs. 40,000, under the current Income Tax Act.
In this guide to tax benefits of life insurance in Nepal, you'll learn just how that deduction is determined and applied and how, effectively, a portion of your premium is deducted each year you keep the policy in force.
Bonus is also accrued as a value advantage of the participating plan over time, in addition to the base sum assured. You can check the SuryaJyoti bonus rate and understand how it will contribute to the ultimate payout on a savings-linked policy.
The calculations SuryaJyoti provides are premium calculations based on an actuarial framework approved by the NIA and applicable to all life insurers in Nepal.
The Nepal Insurance Authority, established under Section 3 of the Insurance Act 2079, regulates premium structures, solvency margins, and actuarial practices across all 14 operating life insurers in Nepal.
This ensures that the premium you are quoted is based on a standardised, audited methodology rather than arbitrary pricing.
The fastest way to view your specific premium is to use the SuryaJyoti Premium Calculator.
Just fill in the details regarding your age, the amount of cover you want, the plan type, and the term of your policy, and you'll instantly get a quote without any obligation.
For riders, the Insurance FAQs explain the cost of each rider added to the base.
To know which plan and sum assured are suitable for your income and goals, SuryaJyoti agents available across its 200 branches in Nepal are within reach through the network points finder.
You can also apply directly from the online application form and pay premiums via eSewa, Khalti, FonePay, ConnectIPS, or NIC Asia Bank through the online payment page.
Premium is calculated using three components: the mortality charge based on age and health, the savings element for endowment and money back plans, and an expense loading for operational costs.
Yes, it is the single biggest factor. Older applicants pay higher premiums because the actuarial probability of a claim is higher.
Yes. A medical examination is required for policies above a certain sum assured. Pre-existing conditions like hypertension or diabetes may result in an extra loading on the standard premium, or exclusion of specific conditions.
Significantly. Term plans carry the lowest premiums because they cover only mortality risk. Endowment and money back plans carry higher premiums because they also fund a savings corpus that matures with the policy.
Generally yes. Women statistically have longer life expectancies, resulting in a lower mortality charge for the same age and sum assured compared to men.
By understanding how life insurance premiums are calculated in Nepal, you have a better chance of understanding what exactly you're paying for and why.
The premium is not a fabricated figure, it depends on several factors, including your age, your health, the type of coverage you choose, and the type of plan you select.
It is calculated within a regulatory framework that is audited and approved by the Nepal Insurance Authority.
The best thing you can do with that information is act on it early. Each year you wait increases your entry age and raises the premium for the same life coverage.
Every rider added thoughtfully strengthens the plan. Every sum assured calculated correctly means the premium you pay is actually working in proportion to the risk you face.
If you are still deciding between plan types, the guide on best endowment insurance plans in Nepal and the breakdown of money back insurance plans in Nepal are the right next reads.
And for those approaching this entirely fresh, the beginner's guide to life insurance in Nepal covers every foundational concept before you compare premiums.
The right premium is the one that gives your family the right coverage, and the best time to lock it in is now. Get Your Life Insurance Today →
 Services


 Transparency Dashboard